Experts Clear the Air on UPI Payment Confusion
Merchants and consumers are a weary of the latest UPI payment rules, many shopkeepers are insisting on cash only. Financial gurus give some practical and legal advice
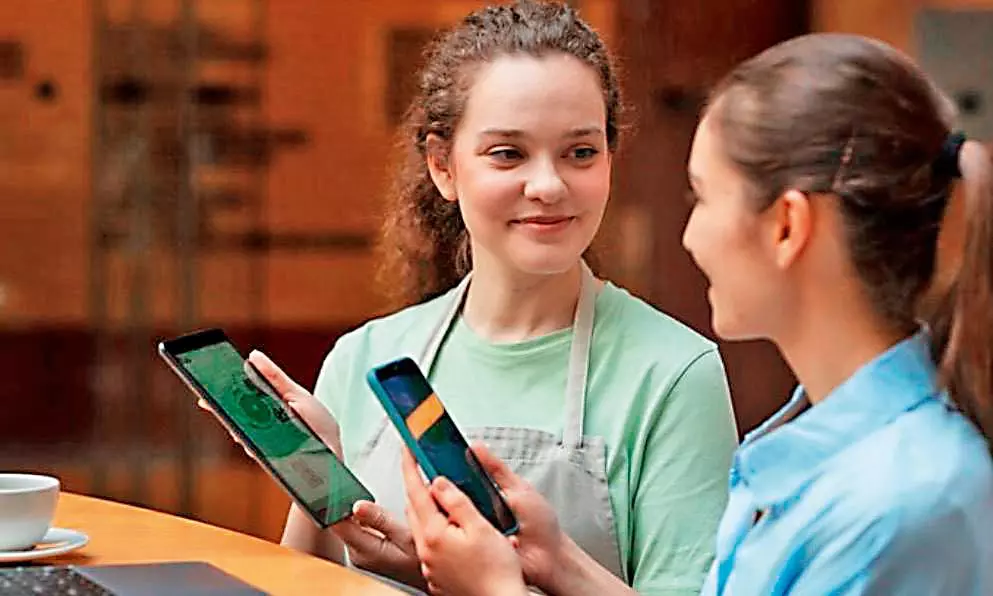
For millions of Indians, the UPI payment service has become an intricate part of their daily life. No wallet, no cash, just a simple scan and pay. However, from October 15, eligible UPI payments above Rs 2,000 to merchants will attract a 0.4% MDR (Merchant Discount Rate). The charge is on the merchant, not the consumer; person-to-person payments remain free. Although the Government has clarified this, there is still a lot of confusion and hullabaloo among the masses. The question on everybody’s mind is: Why the charge, and who will eventually foot the bill?
Money Matters
“A 0.4% charge looks small in percentage terms, but the merchant will assess it against profit, not turnover,” says Basesh Gala, Managing Partner & Founder, 39 Solutions LLP (RiSE).
Merchant Discount Rate (MDR) is a small fee charged on certain digital payments made to merchants. The cost a shopkeeper bears for accepting a digital payment, not a fee the customer is meant to pay. Basesh says that UPI has been free so far. “When your benchmark is zero,” he points out, “even 0.4% becomes a cost worth counting.”
Every Penny Counts
The MDR has existed on debit-card transactions as well, and in practice, the cost is very rarely passed on to consumers explicitly. Anirudh Rapole, a CA, Entrepreneur & Content Creator says, “On paper, merchants are not permitted to pass MDR onto consumers and consumers only pay the listed price.” In practice, however, he says there could be some leakage, as has been seen with card payments. Rather than appearing as an explicit “UPI surcharge”, he expects it to show up more subtly, through cash discounts, or fewer offers and incentives for customers who choose to pay digitally.
Rates & Dates
Referring to the Finance Ministry’s clarification dated September 15, 2026, Basesh notes that the standard charge applies to eligible merchant transactions above Rs 2,000, capped at Rs 300 per transaction. Payments up to Rs 2,000, along with qualifying micro-merchants receiving up to Rs 1 lakh a month under the P2PM category, remain exempt.
The Ministry estimates that 96% of merchant transactions by number will remain unaffected.
Expert View
Deepanshu Onkar, a Senior Analyst in the field of Economics & Market Research expects a behavioural shift among consumers, particularly for higher-value purchases. He, however, does not expect the everyday UPI habit to be seriously disrupted. Deepanshu says, “UPI has become a high-frequency payment rail, and FY26 data shows that 86% of P2M transactions were below ?500.”
So, while everyday UPI use may remain unchanged, merchants handling bigger payments may start looking closely at the cost of accepting them. Transactions of payments above Rs 2,000 make up only about 4% of P2M volumes but nearly two-thirds of their value.
Experts feel the impact could vary significantly across sectors. For fuel and telecom, for instance, eligible transactions above Rs 2,000 attract a flat Rs 5 MDR, which should keep the impact relatively contained.
The Cost Factor
The government has made it clear that consumers should not be charged MDR directly, and banks must ensure merchants do not pass it on. Ravinder Singh, author and entrepreneur recalls a recent visit to a local store, where he bought sanitary fittings for his bathroom. When he offered to pay by credit card, the merchant told him there would be an extra 2% charge. “It can be legally disputed, but at what cost would one be willing to do this?” he asks.
Ravinder worries UPI could now see a smaller version of the same thing. Merchants could factor the cost into prices or simply prefer other payment methods. Some online platforms already charge “convenience fees” and “platform fees.”
If merchants stop accepting UPI payments, then consumers would have no other option but to pay them in cash. Most buyers prefer credit cards for high-value purchases because they are rewarded with points.
The Legal Angle
Legally, the line is clear. The National Payments Corporation of India (NPCI) has clarified that merchants cannot pass the MDR on to consumers through a separate charge. But what about indirect recovery? What if a merchant quietly increases prices or withdraws discount for UPI payments?
Adv. Pradeep Nambiar, General Secretary, Investors & Consumer Guidance Society believes market competition could act as a check. With consumers having multiple ways to pay and merchants competing for business, he expects market forces to limit arbitrary price increases or recoveries linked to UPI. There is also the Rs 300 cap on standard MDR as an added safeguard for consumers. He says, “There cannot be any huge consumer violation as market conditions help consumers to buy products at best prices.”
Interesting Points
Adv. Siddharth Chandrashekhar, Senior Panel Counsel for the Department of Revenue Intelligence, Bombay High Court, says, “If a merchant tries to charge any fee beyond 0.4%, it can very likely lead to a breach of the agreement the merchant has with the bank and could also constitute an unfair trade practice under the Consumer Protection Act, 2019.”
But Adv. Siddharth points out that merchants can choose not to accept UPI at all if they want to avoid the MDR. He draws from his own experience with American Express cards, which many merchants do not accept because they require a separate machine and come with a higher fee for the merchant. In such cases, customers are simply asked to pay through another mode or in cash.
The rules, however, are different for larger businesses. Merchants with a turnover above Rs 50 crore are required to offer prescribed electronic payment modes, including UPI, without charging customers. For them, refusing UPI could amount to a violation. For smaller merchants, Siddharth says, choosing not to accept UPI remains a legal commercial choice.
UPI Transaction Gyaan
· P2P (Peer-to-Peer) UPI payments remain FREE, regardless of the amount.
· 0.4% MDR applies to specified merchant transactions above Rs 2,000 subject to a Rs 300 cap for transactions of Rs 75,000 and above.
· Small merchants remain protected under the zero-MDR framework, including eligible vendors receiving up to Rs 1 lakh a month via UPI QR.
· Consumers cannot be charged the MDR; banks have been advised to ensure merchants don’t pass it on.
· Rules would be implemented from 15th October, 2026.
What is clear is this:
For consumers, if there’s no UPI, there’s no legal compulsion to make it happen. Better choice: Keep some cash handy because when the QR doesn’t scan, cash still works!
If the merchant says, I don’t want UPI, we would have no other option but to pay them in cash.”
Ravinder Singh, Author & Entrepreneur
“There cannot be any huge consumer violation as market conditions help consumers to buy products at best prices.”
Adv. Pradeep Nambiar, Gen Secy, Investors & Consumer Guidance Society
When your benchmark is 0, even 0.4% becomes a cost worth counting.”
Basesh Gala, Managing Partner & Founder, 39 Solutions LLP (RiSE)