Knowing About SIPs is Not the Same as Having a Financial Plan

7 Nov 2026 3:59 PM IST7 Nov 2026 3:59 PM IST
Neha Nagar, finance content creator and co-author of Simple Money, Serious Wealth, discusses why rising investment awareness has not translated into financial discipline, the importance of goal-based planning and the common money mistakes that can affect long-term wealth creation.
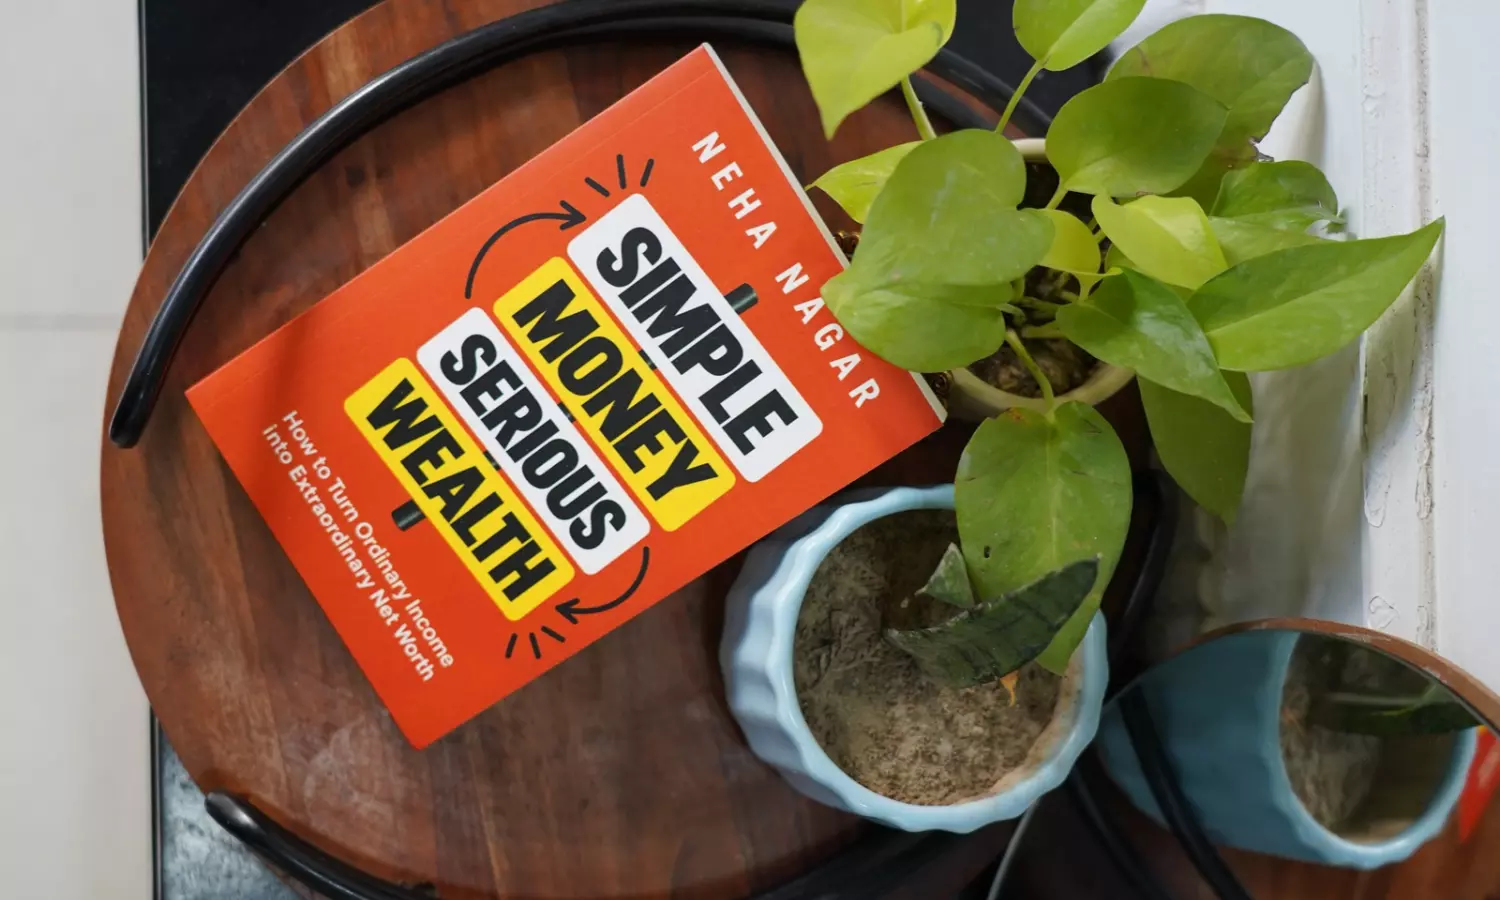
Simple Money Serious Wealth by Neha Nagar
With more Indians investing in mutual funds, SIPs and other financial products, the gap between knowing about money and managing it effectively remains a concern. In a conversation with Deccan Chronicle, finance educator and author Neha Nagar discusses the importance of financial planning, navigating social media advice, avoiding common money mistakes and building wealth around individual goals and responsibilities.
Why do you think financial awareness has increased in India, but financial discipline and planning haven't kept pace?
People are investing more than ever, but many struggle to stay invested. In September 2026, SIP investments reached ₹32,490 crore, yet around 78 out of every 100 new SIPs started that month were stopped or closed. Many people invest after watching a reel or following advice without having a clear plan. When unexpected expenses or market falls occur, they don't know what to do next. This gap between awareness and action was one of the reasons CA Deepak Bhati and I wrote Simple Money, Serious Wealth.
Many people know about SIPs, mutual funds and insurance, but don't know how these fit into their lives. Where do you think they are going wrong?
Having investments doesn't always mean being financially prepared. I often meet people who have SIPs but no emergency fund, or insurance without enough coverage. The first step is to understand your priorities, build an emergency fund and get adequate insurance. Investments should then be chosen according to your goals, income and responsibilities.
How can people distinguish between genuinely useful financial advice and the noise created by finance influencers on social media?
People should ask three questions before following financial advice: Is the person explaining why or simply telling me what to buy? Are they discussing risks as well as returns? Do they have a financial interest in the product? SEBI found that around 93% of individual F&O traders lost money between FY22 and FY24. This shows why understanding risks matters. Social media can introduce people to financial concepts, but decisions need careful thought.
Why do so many Indians approach investing before understanding their financial goals, risk appetite and responsibilities?
People often focus on returns before deciding what they are investing for. Before choosing a product, ask yourself when you will need the money and how much risk you can take. Saving for a house in three years requires a different approach from investing for retirement 30 years away. Your income and family responsibilities should also guide your decisions.
Neha Nagar
How should financial planning change as people move through different life stages, from their first salary to marriage, parenthood and retirement?
With your first salary, build an emergency fund, get health insurance and start saving regularly. At marriage, discuss finances and future goals with your partner. Parenthood calls for reviewing insurance and planning for education expenses. As retirement approaches, focus on protecting your savings and clearing loans. Review your plan every year. I co-authored Simple Money, Serious Wealth with CA Deepak Bhati, published by 1 Finance, to make financial planning easier to understand. At our book launch, I was glad to see readers in their 60s and 70s picking it up for themselves and their families. It's never too late to learn.
What are some of the most common money mistakes you have encountered among Indians, and which ones can have the biggest long-term consequences?
Some common mistakes are being underinsured, borrowing to maintain a lifestyle, blindly trusting others with financial decisions and chasing quick returns. Another is delaying investments while waiting to earn more. Starting early, asking questions and understanding where your money goes can make a significant difference over time. Of these mistakes, delaying your financial journey can be especially costly because lost compounding time cannot be recovered.
( Source : Deccan Chronicle )
Next Story